Limits over time
The exemption, the income limits and the asset limit since 1976
In brief
Each step on these charts is a town vote. The income limits have not moved since 2012, and the exemption amounts and asset limit have not moved since 2006.
- $35,000Income limit, single (set March 2012, still in effect)
- $49,000Income limit, married couple (set March 2012, still in effect)
- $150,000Asset limit, not counting the home (single; married combined is the same)
- Married couple (now $49,000)
- Single (now $35,000)
Source: Rindge Annual Town Report 1982; Rindge Annual Town Report 1983; Rindge Annual Town Report 1996; Rindge Annual Town Report 1997; Rindge Annual Town Report 2006; Rindge Annual Town Report 2011; Rindge Annual Town Report 2012
Show the data table
| Year of vote | Series | Amount |
|---|---|---|
| 1983 | Married couple | $12,000 |
| 1997 | Married couple | $27,072 |
| 2006 | Married couple | $35,000 |
| 2012 | Married couple | $49,000 |
| 1983 | Single | $10,000 |
| 1997 | Single | $18,940 |
| 2006 | Single | $25,000 |
| 2012 | Single | $35,000 |
- Asset limit (not counting the home) (now $150,000)
- Exemption, age 80+ (now $200,000)
- Exemption, ages 65-74 (now $100,000)
Source: Rindge Annual Town Report 1977; Rindge Annual Town Report 1978; Rindge Annual Town Report 1982; Rindge Annual Town Report 1983; Rindge Annual Town Report 1990; Rindge Annual Town Report 1996; Rindge Annual Town Report 1997; Rindge Annual Town Report 2006
Show the data table
| Year of vote | Series | Amount |
|---|---|---|
| 1976 | Asset limit (not counting the home) | $35,000 |
| 1978 | Asset limit (not counting the home) | $50,000 |
| 1983 | Asset limit (not counting the home) | $30,000 |
| 1997 | Asset limit (not counting the home) | $50,000 |
| 2006 | Asset limit (not counting the home) | $150,000 |
| 1983 | Exemption, age 80+ | $20,000 |
| 1990 | Exemption, age 80+ | $100,000 |
| 2006 | Exemption, age 80+ | $200,000 |
| 1983 | Exemption, ages 65-74 | $10,000 |
| 1990 | Exemption, ages 65-74 | $50,000 |
| 2006 | Exemption, ages 65-74 | $100,000 |
At each vote
| Vote | 65–74 | 75–79 | 80+ | Income, single | Income, married | Asset limit |
|---|---|---|---|---|---|---|
| Before 1978 | — | — | — | — | — | $35,000 |
| 1978 | — | — | — | — | — | $50,000 |
| 1983 | $10,000 | $15,000 | $20,000 | under $10,000 | under $12,000 | $30,000 |
| 1990 | $50,000 | $70,000 | $100,000 | — | — | — |
| 1997 | — | — | — | $18,940 | $27,072 | $50,000 |
| 2006 | $100,000 | $140,000 | $200,000 | $25,000 | $35,000 | $150,000 |
| 2012 | — | — | — | $35,000 | $49,000* | — |
* The 2020 MS-1 lists $50,000, which appears to be a reporting error; the 2012 vote and 2025 MS-1 both say $49,000. [Source: Rindge report 2020, 2020 MS-1, pdf p.70] [Source: Rindge report 2012; Rindge report 2025, 2012 Art. 20; 2025 MS-1, pdf p.91]
The 1983 limit of $30,000 excluded the residence and was lower than the $50,000 “assets of any kind” limit adopted in 1978. The pre-1978 limit of $35,000 is the limit named in the 1978 article; no 1976 document states it. A dash means that vote did not set this item (or the town report summary does not state it); the earlier amount is assumed to carry forward, and the charts draw it that way. 2012 limits are still in effect today. Sources for each vote are on the Votes page.
The wording that set each limit
Warrant articles and minutes as printed, oldest first, ending with the 2025 MS-1 form that shows the limits in force today. Tap an image to zoom in.
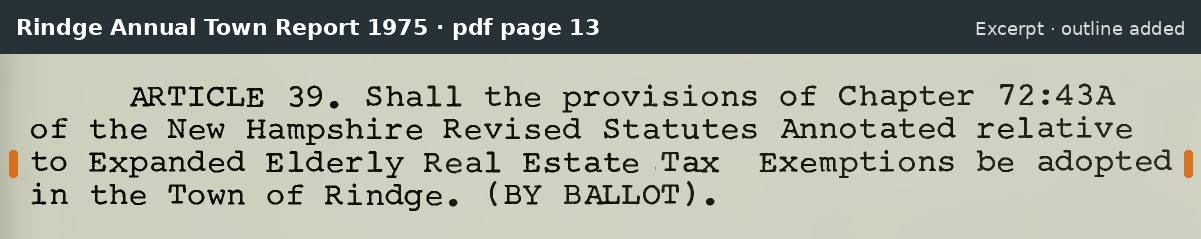
1976 warrant, Article 39 (in the 1975 report)
Typed wording from this image
ARTICLE 39. Shall the provisions of Chapter 72:43A
of the New Hampshire Revised Statutes Annotated relative
to Expanded Elderly Real Estate Tax Exemptions be adopted
in the Town of Rindge. (BY BALLOT).
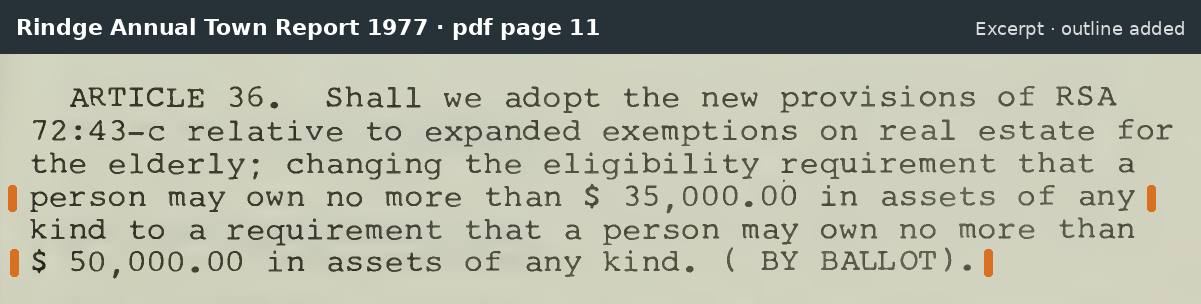
1978 warrant, Article 36: assets limit $35,000 to $50,000
Typed wording from this image
ARTICLE 36. Shall we adopt the new provisions of RSA
72:43-c relative to expanded exemptions on real estate for
the elderly; changing the eligibility requirement that a
person may own no more than $ 35,000.00 in assets of any
kind to a requirement that a person may own no more than
$ 50,000.00 in assets of any kind. ( BY BALLOT).
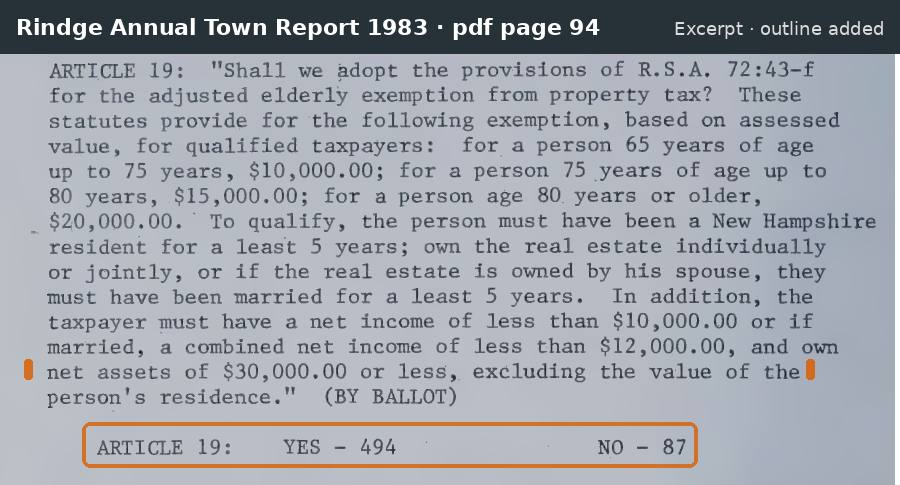
1983 Town Meeting, Article 19: Yes 494, No 87
Typed wording from this image
ARTICLE 19: "Shall we adopt the provisions of R.S.A. 72:43-f
for the adjusted elderly exemption from property tax? These
statutes provide for the following exemption, based on assessed
value, for qualified taxpayers: for a person 65 years of age
up to 75 years, $10,000.00; for a person 75 years of age up to
80 years, $15,000.00; for a person age 80 years or older,
$20,000.00. To qualify, the person must have been a New Hampshire
resident for a least [sic] 5 years; own the real estate individually
or jointly, or if the real estate is owned by his spouse, they
must have been married for a least [sic] 5 years. In addition, the
taxpayer must have a net income of less than $10,000.00 or if
married, a combined net income of less than $12,000.00, and own
net assets of $30,000.00 or less, excluding the value of the
person's residence." (BY BALLOT)
ARTICLE 19: YES - 494 NO - 87
A stray mark before "$20,000.00" in the scan is not transcribed. The text layer of this scan misreads the No count as "-— -87"; the page image reads "NO - 87".
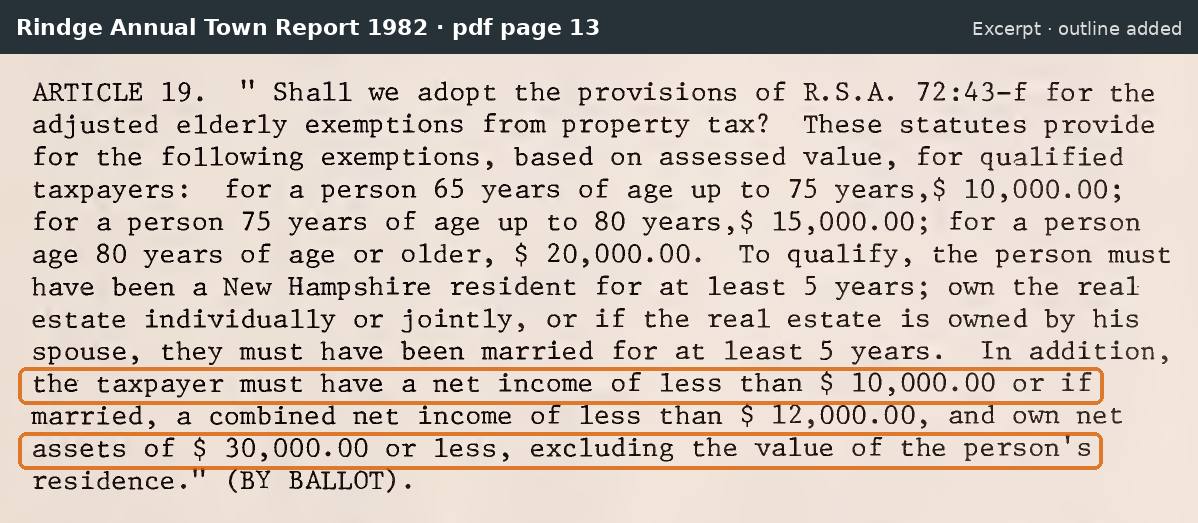
1983 warrant, Article 19 (in the 1982 report)
Typed wording from this image
ARTICLE 19. " Shall we adopt the provisions of R.S.A. 72:43-f for the
adjusted elderly exemptions from property tax? These statutes provide
for the following exemptions, based on assessed value, for qualified
taxpayers: for a person 65 years of age up to 75 years,$ 10,000.00;
for a person 75 years of age up to 80 years,$ 15,000.00; for a person
age 80 years of age or older, $ 20,000.00. To qualify, the person must
have been a New Hampshire resident for at least 5 years; own the real
estate individually or jointly, or if the real estate is owned by his
spouse, they must have been married for at least 5 years. In addition,
the taxpayer must have a net income of less than $ 10,000.00 or if
married, a combined net income of less than $ 12,000.00, and own net
assets of $ 30,000.00 or less, excluding the value of the person's
residence." (BY BALLOT).
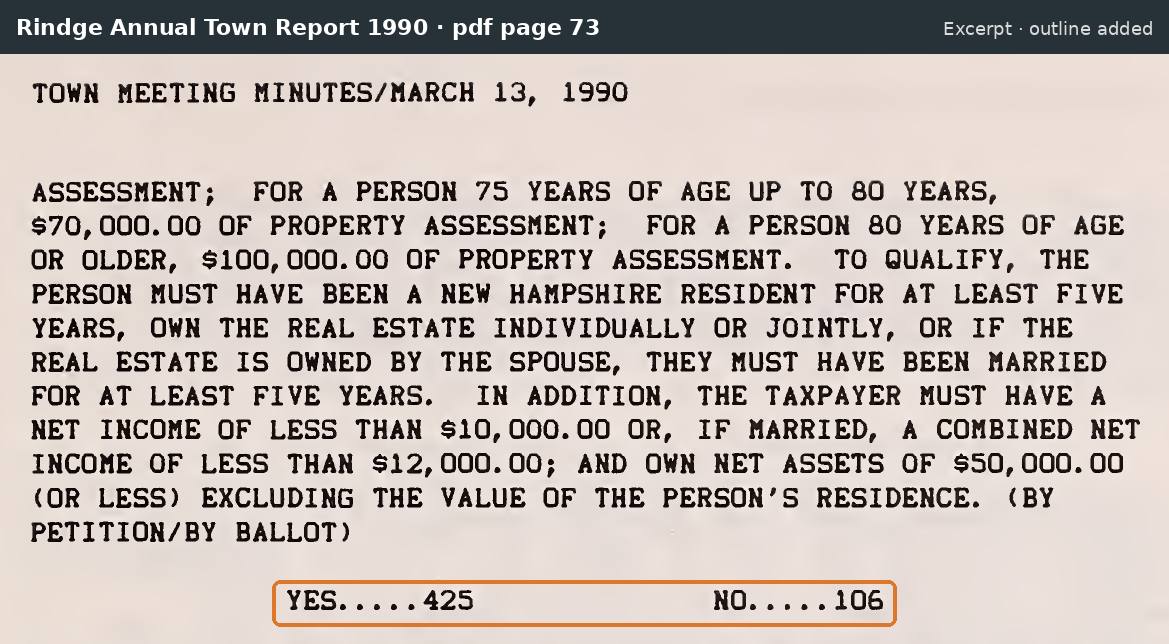
1990 Town Meeting, Article 27: Yes 425, No 106
Typed wording from this image
TOWN MEETING MINUTES/MARCH 13, 1990
ASSESSMENT; FOR A PERSON 75 YEARS OF AGE UP TO 80 YEARS,
$70,000.00 OF PROPERTY ASSESSMENT; FOR A PERSON 80 YEARS OF AGE
OR OLDER, $100,000.00 OF PROPERTY ASSESSMENT. TO QUALIFY, THE
PERSON MUST HAVE BEEN A NEW HAMPSHIRE RESIDENT FOR AT LEAST FIVE
YEARS, OWN THE REAL ESTATE INDIVIDUALLY OR JOINTLY, OR IF THE
REAL ESTATE IS OWNED BY THE SPOUSE, THEY MUST HAVE BEEN MARRIED
FOR AT LEAST FIVE YEARS. IN ADDITION, THE TAXPAYER MUST HAVE A
NET INCOME OF LESS THAN $10,000.00 OR, IF MARRIED, A COMBINED NET
INCOME OF LESS THAN $12,000.00; AND OWN NET ASSETS OF $50,000.00
(OR LESS) EXCLUDING THE VALUE OF THE PERSON'S RESIDENCE. (BY
PETITION/BY BALLOT)
YES.....425 NO.....106
The article begins on the previous page (pdf p.72, included in the hosted excerpt).
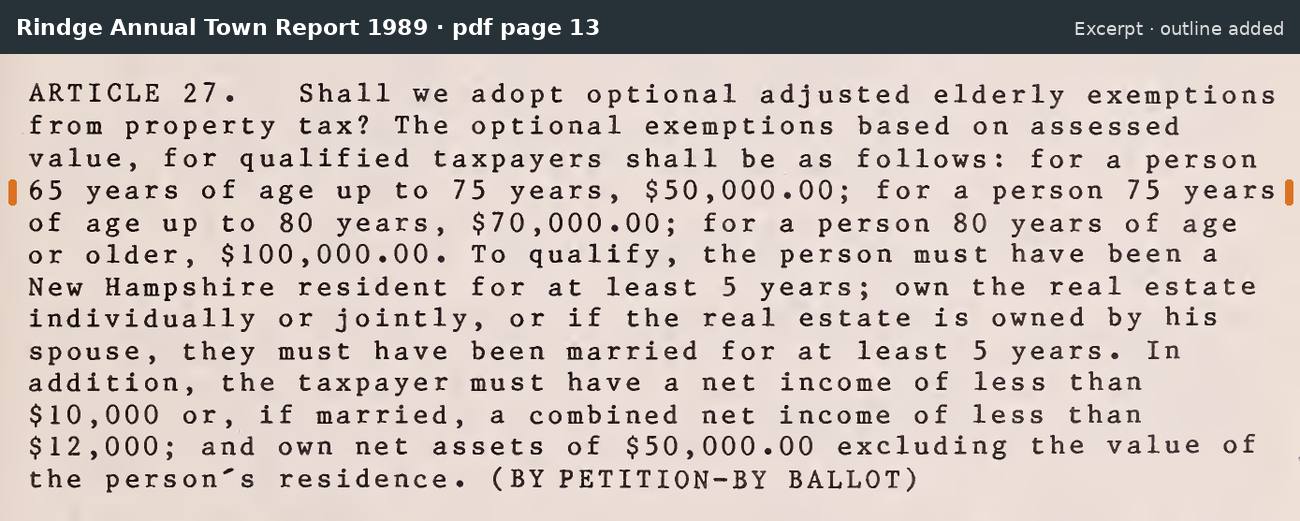
1990 warrant, Article 27 (in the 1989 report)
Typed wording from this image
ARTICLE 27. Shall we adopt optional adjusted elderly exemptions
from property tax? The optional exemptions based on assessed
value, for qualified taxpayers shall be as follows: for a person
65 years of age up to 75 years, $50,000.00; for a person 75 years
of age up to 80 years, $70,000.00; for a person 80 years of age
or older, $100,000.00. To qualify, the person must have been a
New Hampshire resident for at least 5 years; own the real estate
individually or jointly, or if the real estate is owned by his
spouse, they must have been married for at least 5 years. In
addition, the taxpayer must have a net income of less than
$10,000 or, if married, a combined net income of less than
$12,000; and own net assets of $50,000.00 excluding the value of
the person's residence. (BY PETITION-BY BALLOT)
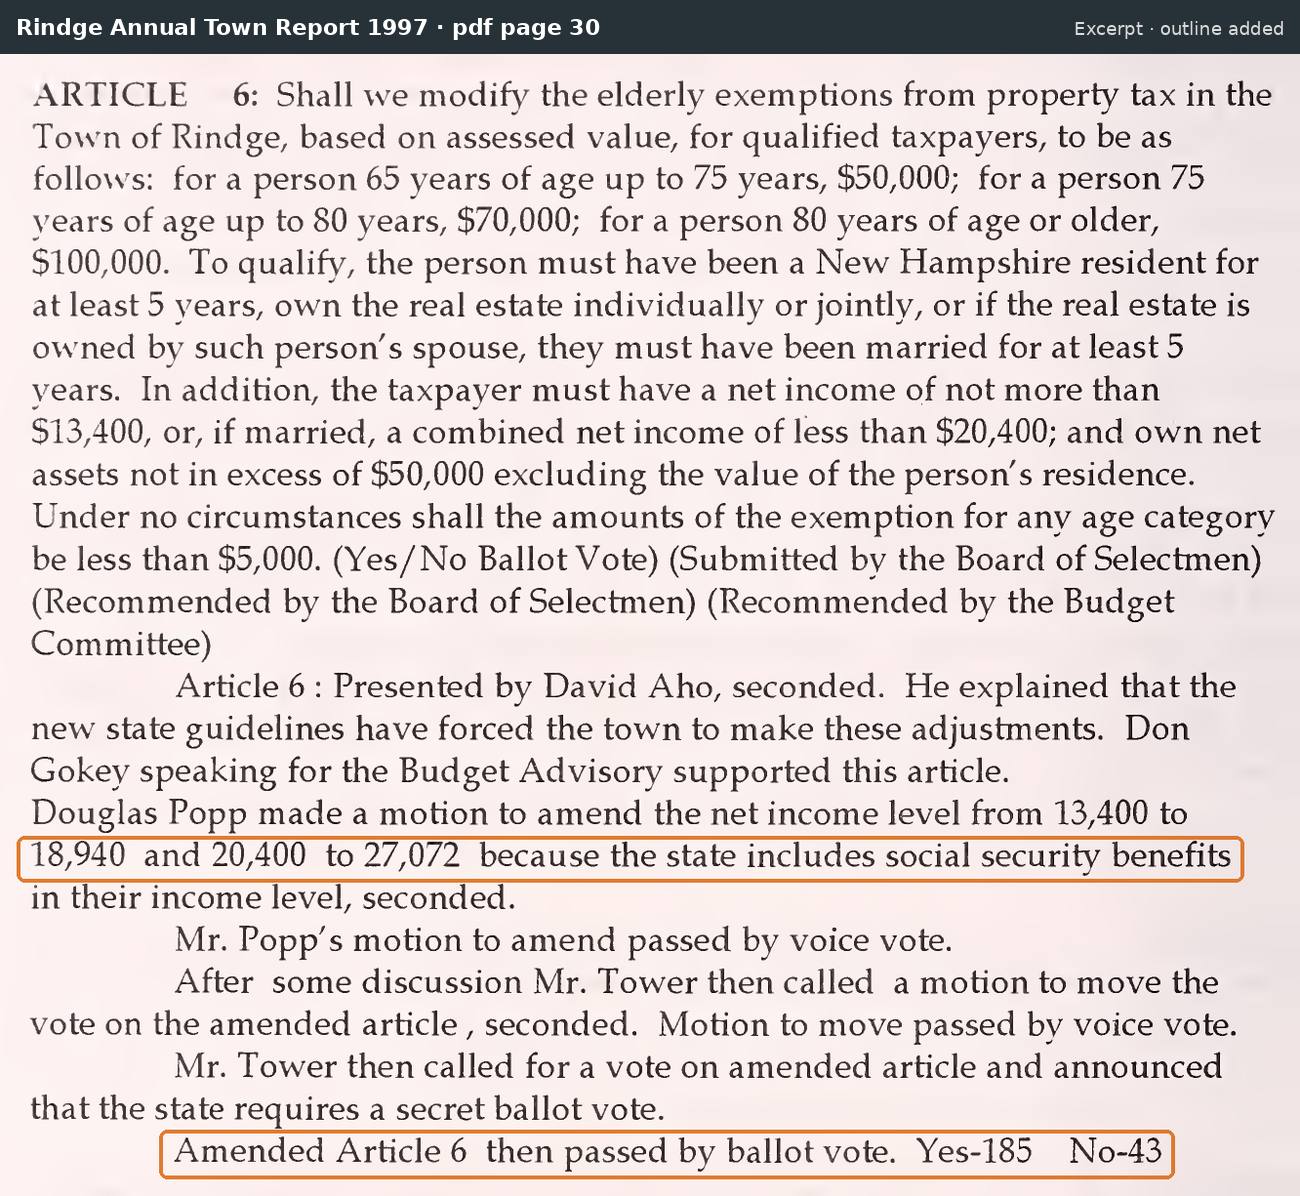
1997 Town Meeting, amended Article 6: Yes 185, No 43
Typed wording from this image
ARTICLE 6: Shall we modify the elderly exemptions from property tax in the
Town of Rindge, based on assessed value, for qualified taxpayers, to be as
follows: for a person 65 years of age up to 75 years, $50,000; for a person 75
years of age up to 80 years, $70,000; for a person 80 years of age or older,
$100,000. To qualify, the person must have been a New Hampshire resident for
at least 5 years, own the real estate individually or jointly, or if the real estate is
owned by such person's spouse, they must have been married for at least 5
years. In addition, the taxpayer must have a net income of not more than
$13,400, or, if married, a combined net income of less than $20,400; and own net
assets not in excess of $50,000 excluding the value of the person's residence.
Under no circumstances shall the amounts of the exemption for any age category
be less than $5,000. (Yes/No Ballot Vote) (Submitted by the Board of Selectmen)
(Recommended by the Board of Selectmen) (Recommended by the Budget
Committee)
Article 6 : Presented by David Aho, seconded. He explained that the
new state guidelines have forced the town to make these adjustments. Don
Gokey speaking for the Budget Advisory supported this article.
Douglas Popp made a motion to amend the net income level from 13,400 to
18,940 and 20,400 to 27,072 because the state includes social security benefits
in their income level, seconded.
Mr. Popp's motion to amend passed by voice vote.
After some discussion Mr. Tower then called a motion to move the
vote on the amended article , seconded. Motion to move passed by voice vote.
Mr. Tower then called for a vote on amended article and announced
that the state requires a secret ballot vote.
Amended Article 6 then passed by ballot vote. Yes-185 No-43
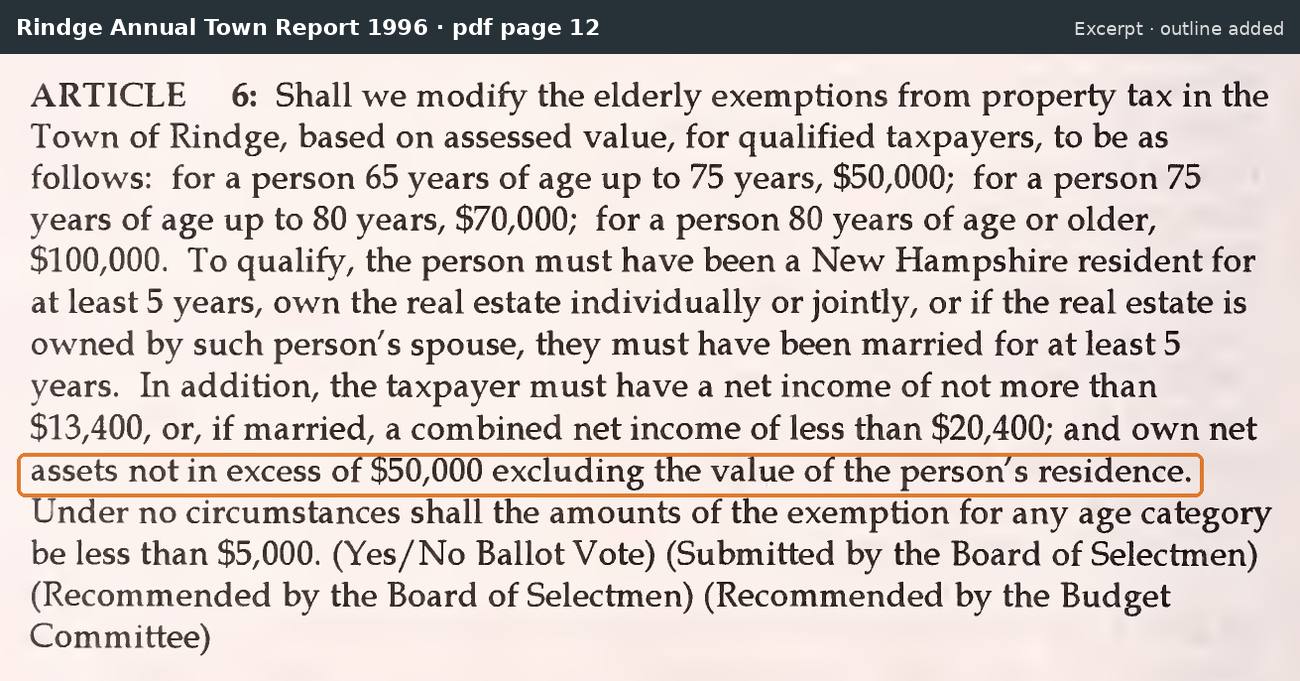
1997 warrant, Article 6 (in the 1996 report)
Typed wording from this image
ARTICLE 6: Shall we modify the elderly exemptions from property tax in the
Town of Rindge, based on assessed value, for qualified taxpayers, to be as
follows: for a person 65 years of age up to 75 years, $50,000; for a person 75
years of age up to 80 years, $70,000; for a person 80 years of age or older,
$100,000. To qualify, the person must have been a New Hampshire resident for
at least 5 years, own the real estate individually or jointly, or if the real estate is
owned by such person's spouse, they must have been married for at least 5
years. In addition, the taxpayer must have a net income of not more than
$13,400, or, if married, a combined net income of less than $20,400; and own net
assets not in excess of $50,000 excluding the value of the person's residence.
Under no circumstances shall the amounts of the exemption for any age category
be less than $5,000. (Yes/ No Ballot Vote) (Submitted by the Board of Selectmen)
(Recommended by the Board of Selectmen) (Recommended by the Budget
Committee)
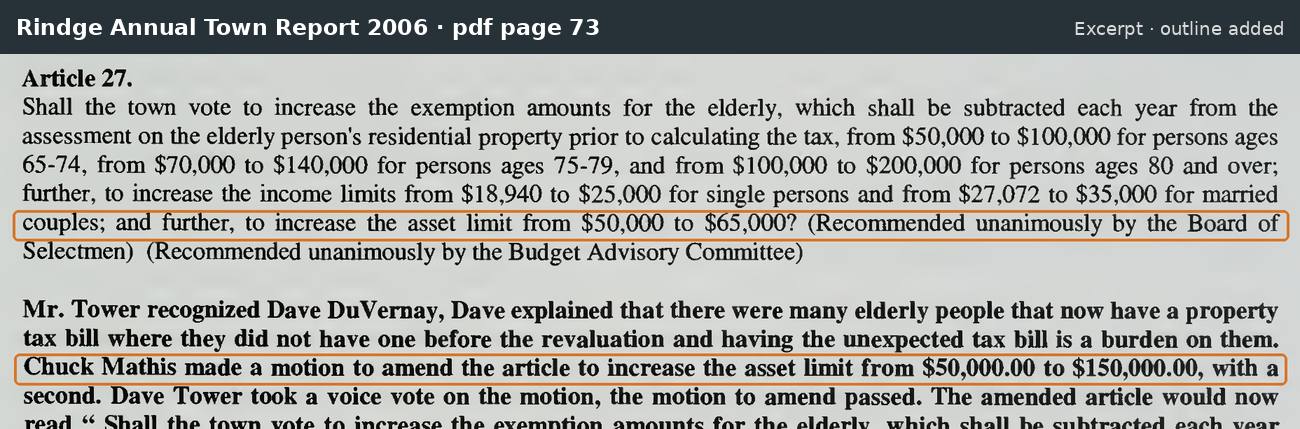
2006 deliberative session minutes, Article 27 (asset limit amended from $65,000 to $150,000)
Typed wording from this image
Article 27.
Shall the town vote to increase the exemption amounts for the elderly, which shall be subtracted each year from the
assessment on the elderly person's residential property prior to calculating the tax, from $50,000 to $100,000 for persons ages
65-74, from $70,000 to $140,000 for persons ages 75-79, and from $100,000 to $200,000 for persons ages 80 and over;
further, to increase the income limits from $18,940 to $25,000 for single persons and from $27,072 to $35,000 for married
couples; and further, to increase the asset limit from $50,000 to $65,000? (Recommended unanimously by the Board of
Selectmen) (Recommended unanimously by the Budget Advisory Committee)
Mr. Tower recognized Dave DuVernay, Dave explained that there were many elderly people that now have a property
tax bill where they did not have one before the revaluation and having the unexpected tax bill is a burden on them.
Chuck Mathis made a motion to amend the article to increase the asset limit from $50,000.00 to $150,000.00, with a
second. Dave Tower took a voice vote on the motion, the motion to amend passed. The amended article would now
read " Shall the town vote to increase the exemption amounts for the elderly, which shall be subtracted each year [cut off at the edge of this crop]
Deliberative session, Feb. 11, 2006. The printed 2006 warrant in the 2005 report already reads $150,000; these minutes show the posted article said $65,000 and was amended.
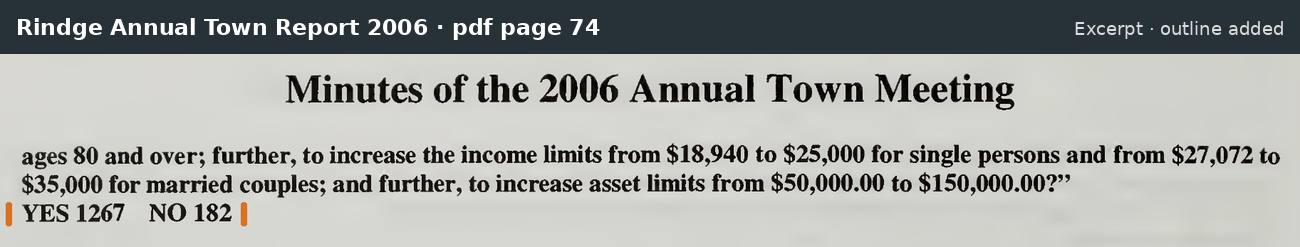
2006 Town Meeting, Article 27: Yes 1,267, No 182
Typed wording from this image
Minutes of the 2006 Annual Town Meeting
ages 80 and over; further, to increase the income limits from $18,940 to $25,000 for single persons and from $27,072 to
$35,000 for married couples; and further, to increase asset limits from $50,000.00 to $150,000.00?"
YES 1267 NO 182
The article begins on the previous page (pdf p.73 of the original, not hosted). Its full wording is in the 2006 warrant excerpt (2005 report).
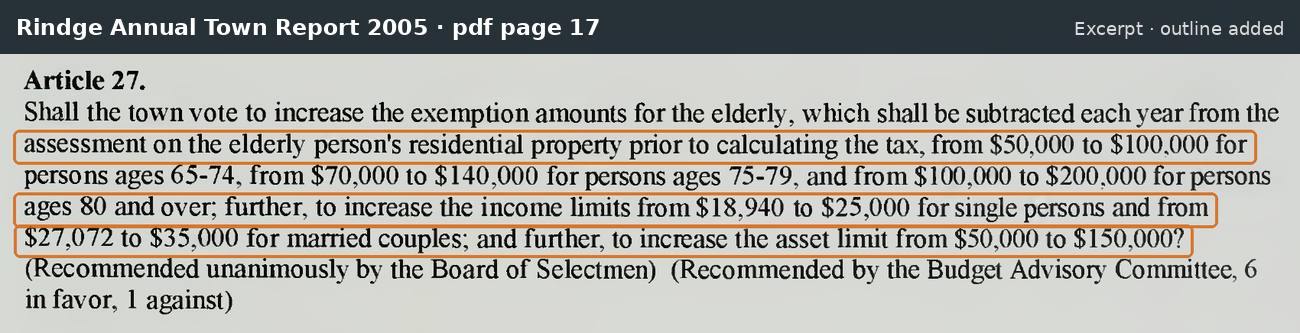
2006 warrant, Article 27 (in the 2005 report)
Typed wording from this image
Article 27.
Shall the town vote to increase the exemption amounts for the elderly, which shall be subtracted each year from the
assessment on the elderly person's residential property prior to calculating the tax, from $50,000 to $100,000 for
persons ages 65-74, from $70,000 to $140,000 for persons ages 75-79, and from $100,000 to $200,000 for persons
ages 80 and over; further, to increase the income limits from $18,940 to $25,000 for single persons and from
$27,072 to $35,000 for married couples; and further, to increase the asset limit from $50,000 to $150,000?
(Recommended unanimously by the Board of Selectmen) (Recommended by the Budget Advisory Committee, 6
in favor, 1 against)
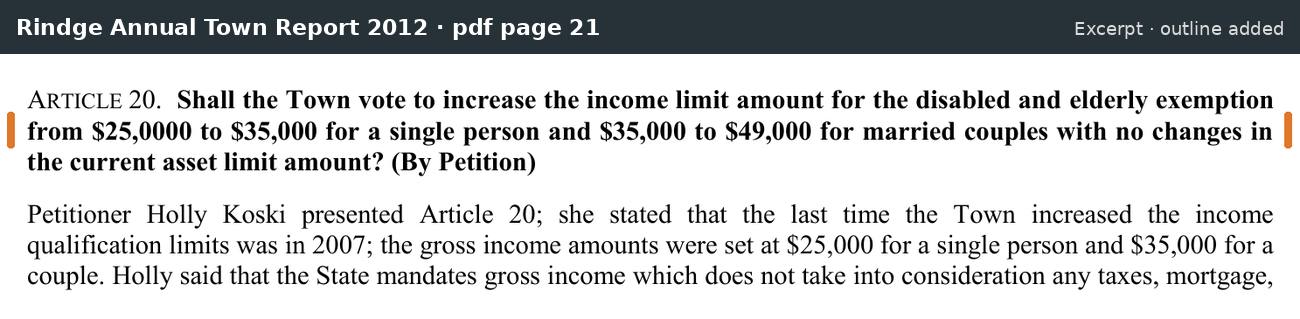
2012 deliberative session minutes, Article 20
Typed wording from this image
ARTICLE 20. Shall the Town vote to increase the income limit amount for the disabled and elderly exemption
from $25,0000 [sic] to $35,000 for a single person and $35,000 to $49,000 for married couples with no changes in
the current asset limit amount? (By Petition)
Petitioner Holly Koski presented Article 20; she stated that the last time the Town increased the income
qualification limits was in 2007; the gross income amounts were set at $25,000 for a single person and $35,000 for a
couple. Holly said that the State mandates gross income which does not take into consideration any taxes, mortgage,
Deliberative session minutes, Feb. 4, 2012. The ballot result for Article 20 is on the next page (see the 2012 vote excerpt).
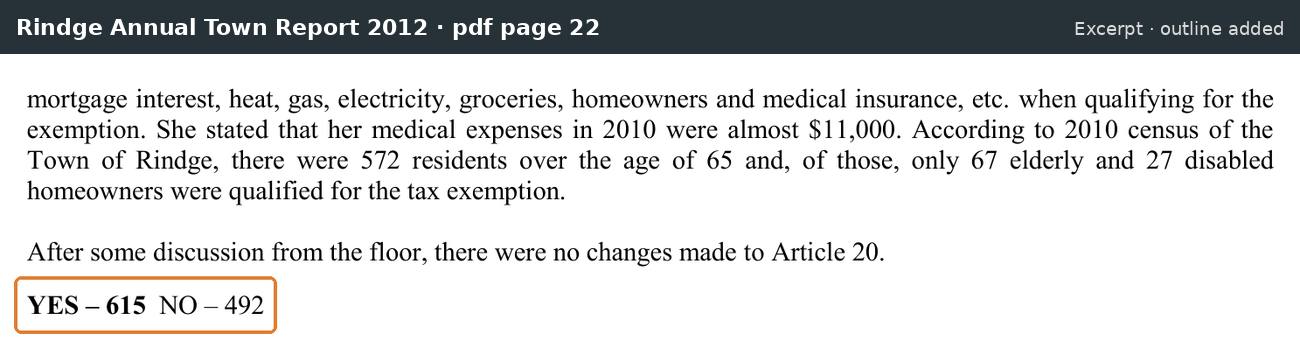
2012 Town Meeting, Article 20: Yes 615, No 492
Typed wording from this image
mortgage interest, heat, gas, electricity, groceries, homeowners and medical insurance, etc. when qualifying for the
exemption. She stated that her medical expenses in 2010 were almost $11,000. According to 2010 census of the
Town of Rindge, there were 572 residents over the age of 65 and, of those, only 67 elderly and 27 disabled
homeowners were qualified for the tax exemption.
After some discussion from the floor, there were no changes made to Article 20.
YES – 615 NO – 492
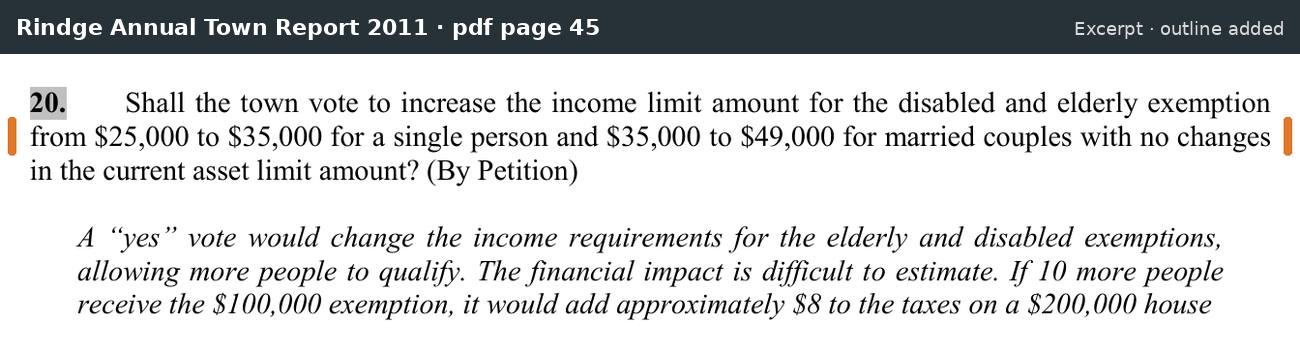
2012 warrant, Article 20 (in the 2011 report)
Typed wording from this image
20. Shall the town vote to increase the income limit amount for the disabled and elderly exemption
from $25,000 to $35,000 for a single person and $35,000 to $49,000 for married couples with no changes
in the current asset limit amount? (By Petition)
A "yes" vote would change the income requirements for the elderly and disabled exemptions,
allowing more people to qualify. The financial impact is difficult to estimate. If 10 more people
receive the $100,000 exemption, it would add approximately $8 to the taxes on a $200,000 house
The page heading ("2012 Town Warrant with Explanations") is above the crop. The explanation sentence continues on the page below the crop.
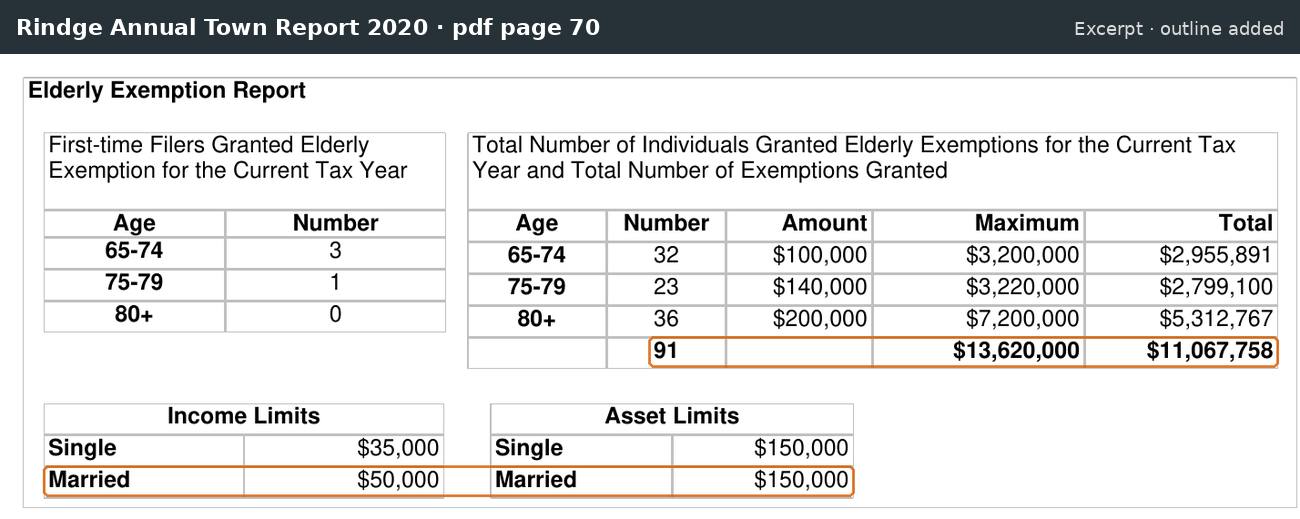
2020 MS-1, Elderly Exemption Report
Typed wording from this image
Elderly Exemption Report
(First-time filers table not transcribed.)
Total Number of Individuals Granted Elderly Exemptions for the Current Tax Year and Total Number of Exemptions Granted
Age | Number | Amount | Maximum | Total
65-74 | 32 | $100,000 | $3,200,000 | $2,955,891
75-79 | 23 | $140,000 | $3,220,000 | $2,799,100
80+ | 36 | $200,000 | $7,200,000 | $5,312,767
(total) | 91 | | $13,620,000 | $11,067,758
Income Limits: Single $35,000 | Married $50,000
Asset Limits: Single $150,000 | Married $150,000
The 2020 MS-1 prints the married income limit as $50,000. The 2012 vote and the 2021-2025 MS-1 forms all say $49,000.
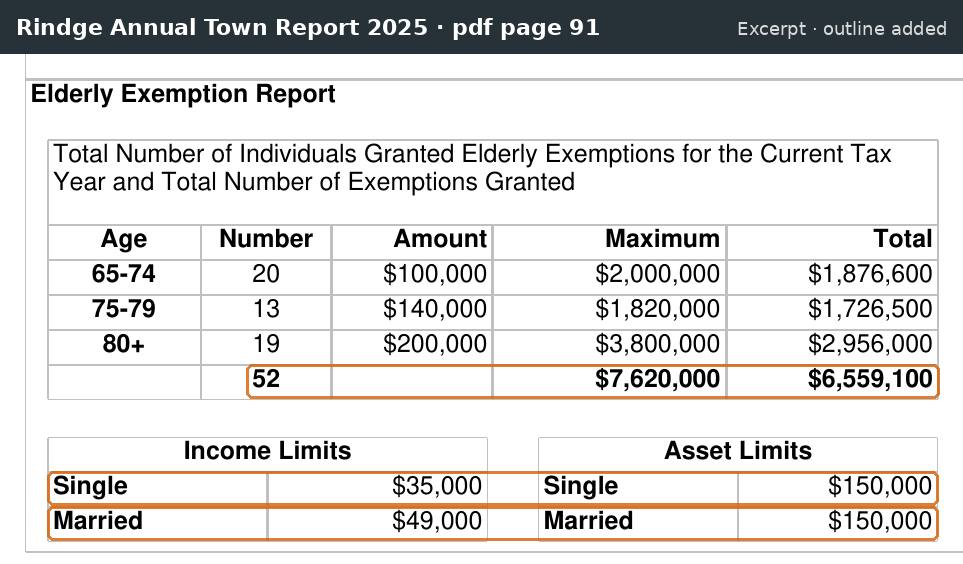
2025 MS-1, Elderly Exemption Report
Typed wording from this image
Elderly Exemption Report
Total Number of Individuals Granted Elderly Exemptions for the Current Tax Year and Total Number of Exemptions Granted
Age | Number | Amount | Maximum | Total
65-74 | 20 | $100,000 | $2,000,000 | $1,876,600
75-79 | 13 | $140,000 | $1,820,000 | $1,726,500
80+ | 19 | $200,000 | $3,800,000 | $2,956,000
(total) | 52 | | $7,620,000 | $6,559,100
Income Limits: Single $35,000 | Married $49,000
Asset Limits: Single $150,000 | Married $150,000